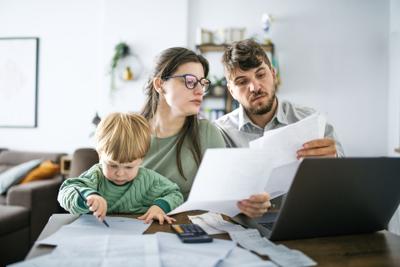

Young family of three with a toddler managing their budget,paying bills and taxes online and calculating monthly expenses at home.Inflation concept.
Thirty-two percent of parents who pay for childcare spend 20 to 29 percent of their household income on it. That figure comes from a national survey of more than 1,000 parents and caregivers, and it looks like a single data point until you run the actual math. Because 20 to 29 percent of income does not mean the same thing to every family. It means something very different depending on whether that income is $55,000 a year or $95,000 a year, and the gap between those two families — in breathing room, in debt exposure, in whether a second child is even a realistic option — is enormous.
Fifty-four percent of survey respondents currently pay for childcare. For the families inside that group, the financial pressure is not abstract. It shows up in the monthly budget every single time.
What 20–29% of Income Means in Real Dollars
People are also reading…
Take a household earning $55,000 a year. After federal and state taxes, take-home pay runs roughly $42,000 to $44,000, depending on the state. If that family is spending 25 percent of gross income on childcare — the midpoint of that 20 to 29 percent range — the childcare bill is $13,750 a year, or about $1,146 a month. That leaves approximately $30,000 to $32,000 in net income to cover everything else: rent or mortgage, groceries, utilities, transportation, health insurance out-of-pocket costs, clothing, and any savings they can manage.
The federal poverty line for a family of three in 2024 sits just above $24,000. So this family is not in poverty, but after childcare, they are working with a monthly remainder in the range of $2,400 to $2,600. Housing alone -- a modest two-bedroom apartment in most mid-size cities -- can consume $1,200 to $1,600 of that. Food, transportation, and utilities take most of what is left.
Move to a household earning $75,000 a year. At 22 percent of gross income, the childcare bill becomes $16,500 a year, or $1,375 a month. Net income after taxes is closer to $57,000 to $60,000. After childcare, this family has roughly $3,300 to $3,600 a month remaining. The math is tighter than the gross income number suggests, but there is marginally more flexibility -- a modest emergency fund is possible, debt repayment is manageable with discipline, and the family is not necessarily choosing between a car repair and a week of groceries.
At $95,000 a year, spending 20 percent of gross income on childcare means a bill of $19,000 annually, or about $1,583 a month. After taxes, net income is closer to $70,000 to $73,000. The monthly remainder after childcare is in the range of $4,200 to $4,500. Housing still commands a large share of that, but this household can realistically service a mortgage, contribute to a retirement account, and absorb unexpected expenses without immediately reaching for a credit card.
Three families, each spending a similar percentage of income on the same category of expense. Completely different outcomes.
The Budget Left Over: What Families Are Working With
The reason this matters beyond the math is what happens when the budget does not stretch far enough. According to Rocket Mortgage's data on the cost of raising kids, 58 percent of parents have gone into debt -- through credit cards or loans -- specifically for child-related expenses. That number is not a surprise when you work through the arithmetic above. For a family at $55,000, an unexpected pediatric bill, a childcare rate increase, or a gap between jobs does not leave much room to absorb the hit.
The same survey found that 24 percent of parents saw their monthly spending increase by $1,000 or more after having children, and 67 percent said raising children costs more than they expected. Thirty-eight percent said it costs "much more" than expected. These are not people who failed to plan. They planned against an estimate that turned out to be wrong once the actual expenses arrived.
Food and household goods ranked as the top cost category at 38 percent, with childcare second at 29 percent. But childcare is the cost with the least flexibility. You can cut a grocery budget. You cannot easily reduce childcare hours if both parents are working, and for single-parent households the calculus is even less forgiving.
How Income Level Changes the Childcare Calculus
The practical consequence of this math is that two families spending the same percentage of income on childcare are not actually in the same situation. For the lower-income household, that spending leaves almost nothing for financial stability, debt reduction, or unexpected costs. For the higher-income household, the percentage is real but manageable.
This is why the delay data is so significant. Fifty percent of survey respondents said they have delayed or avoided having additional children because of financial concerns. That decision does not happen uniformly across income levels. It is concentrated among families where the childcare math is already close to unsustainable -- where adding another child means another $1,100 to $1,400 a month in childcare costs on a budget that is already stretched.
Where the Debt and Delay Data Connect to These Numbers
There is also a housing dimension to this picture. Forty-three percent of parents said they needed more space after having children, and 41 percent pointed to homeownership stability as something they needed. For families spending 20 to 29 percent of gross income on childcare, homeownership is a goal that requires sequencing rather than abandonment. As childcare costs ease when children reach school age, the monthly budget shifts in a meaningful way -- and that shift is often what makes a mortgage payment viable. Down payment assistance programs and flexible loan structures also create earlier entry points for families who want to move before childcare fully resolves.
Forty-six percent of survey respondents said child-related finances cause them stress always or usually. Sixty-one percent are saving for future education costs. Both of those statistics make more sense against the income-level math. Families at the lower end of the income spectrum are simultaneously managing debt, covering childcare, and trying to set aside money for education -- all from a monthly remainder that often runs to only a few hundred dollars after fixed costs.
The percentage of income spent on childcare is a useful policy and planning metric. But the dollar amount left over after that percentage is paid tells the more complete story about which families are managing and which ones are running out of options.